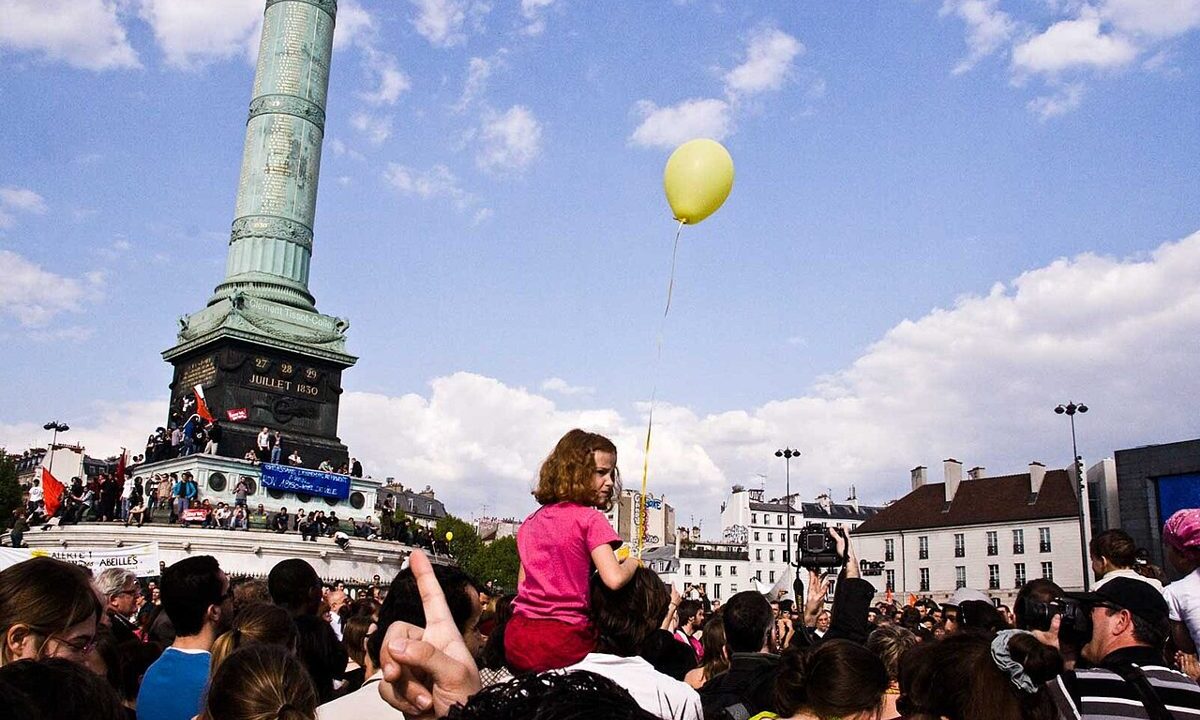
When France debates who should pay for riot damage, insurers are already part of the answer, and their history is instructive. After riots in 2023, insurers paid 793 million euros, about 888 million dollars, on 16,400 claims, according to France Assureurs, the insurers’ federation. That figure, cited in reporting on the current Senate debate, shows the scale of riot damage as an insurance problem before it became a legislative one, and it frames the question now facing the National Assembly: after October 17 damage estimated above 1 billion euros, how much will insurers pay, how much will businesses bear, how much will the state cover, and how much, if the Senate bill becomes law, will be recovered from protesters themselves?
The 2023 precedent matters because it establishes a baseline. Sixteen thousand four hundred claims averaging roughly 48,000 euros each describes damage spread across thousands of businesses, from shattered shopfronts to looted stock to burned premises, rather than a single catastrophic loss. The October 17 unrest, with thousands of shops looted or damaged, nearly 2,400 arrests in one weekend and fire gutting Limoges’ 19th century city hall, is larger in scale, with damage above 1 billion euros, and the insurance bill will likely exceed the 2023 total. But insurance does not cover everything: deductibles, exclusions, underinsurance and uninsured losses all leave gaps, and those gaps are where the political argument about protester liability begins.
The gap the bill tries to fill
The Senate bill, passed on October 28 by 229 votes to 105, would make protesters pay up to 10,000 euros for damage during demonstrations, with joint liability for knowingly participating in a violent group, and with deductions possible from family allowances, housing aid and other benefits once a court ruling is final. Supporters present the bill as filling the gap left by insurance and by offenders’ limited seizable income: if insurers pay businesses and the state pays for public buildings, someone should still bear the cost of the damage itself, and that someone should be the people who caused it. Critics present the same gap differently: insurance already spreads riot losses across policyholders, the state already bears public losses, and adding individual liability, especially deducted from benefits, punishes households for acts they did not personally commit.
The Senate’s own report acknowledges the collection problem: offenders often have little money, or income the law protects from seizure, which is why the bill reaches into benefits at all. Communist Senator Fabien Gay cited monthly deductions of 57 euros from a household receiving RSA, France’s minimum income benefit; at that rate, repaying 10,000 euros would take nearly 15 years. That arithmetic shows the bill’s practical limit: even if liability is established, recovery will be slow, partial and administratively costly, and the amounts recovered from individuals will be a fraction of a billion euro total. The French bill for a riot could soon be paid from a family’s housing aid, and the insurance precedent shows why that mechanism was chosen: conventional recovery from offenders does not yield much.
What the Assembly must decide
The National Assembly, where the bill now goes and where no bloc holds a majority, must decide not only whether protester liability is just but whether it is workable alongside insurance. Amendments could cap deductions, exempt certain benefits, require proof of individual contribution to damage, or prioritise insurer recovery over state recovery. Trade unions and student groups warned in Le Monde of a serious infringement on the freedom to demonstrate, and Amnesty International urged abandonment, while Interior Minister Laurent Nunez stressed the urgency of responding to October 17 chaos. The Assembly debate will test whether those positions can be reconciled in a workable statute, or whether the bill stalls in a divided chamber.
The money trail, from 793 million euros in 2023 to more than 1 billion euros in 2026, tells a story of escalating riot costs that insurance alone has not contained. Whether protester liability contains them, or merely adds a slow, contested recovery mechanism to an already complex distribution of losses, is the question the Assembly must answer. The insurers have already paid their part in 2023. The 2026 bill is still to be decided, and its answer will shape who pays for the next riot as much as for the last one.